

[Dec-2021] Feel PRMIA 8008 Dumps PDF Will likely be The best Option
8008 exam torrent PRMIA study guide
NEW QUESTION 55
According to the Basel II framework, subordinated term debt that was originally issued 4 years ago with a maturity of 6 years is considered a part of:
- A. Tier 3 capital
- B. None of the above
- C. Tier 1 capital
- D. Tier 2 capital
Answer: D
Explanation:
Explanation
According to the Basel II framework, Tier 1 capital, also called core capital or basic equity, includes equity capital and disclosed reserves.
Tier 2 capital, also called supplementary capital, includes undisclosed reserves, revaluation reserves, general provisions/general loan-loss reserves, hybrid debt capital instruments and subordinated term debt issued originally for 5 years or longer.
Tier 3 capital, or short term subordinated debt, is intended only to cover market risk but only at the discretion of their national authority. This only includes short term subordinated debt originally issued for 2 or more years.
An interesting thing to note is the difference between 'subordinated term debt' under Tier 2 and the 'short term subordinated debt' under Tier 3. The distinction is based upon the years to maturity at the time the debt was issued. The remaining time to maturity is not relevant. For the subordinated term debt included under Tier 2, the amount that can be counted towards capital is reduced by 20% for every year when the debt is due within 5 years. This takes care of the time to maturity problem for Tier 2 subordinated debt. For Tier 3 short term subordinated debt, this is not an issue because debt will only qualify for Tier 3 if it has a lock-in clause stipulating that the debt is not required to be repaid if the effect of such repayment is to take the bank below minimum capital requirements.
NEW QUESTION 56
Which of the following statements is true in relation to a normal mixture distribution:
I. Normal mixtures represent one possible solution to the problem of volatility clustering II. A normal mixture VaR will always be greater than that under the assumption of normally distributed returns III. Normal mixtures can be applied to situations where a number of different market scenarios with different probabilities can be expected
- A. I and II
- B. II and III
- C. III
- D. I, II and III
Answer: C
Explanation:
Explanation
Normal mixtures address fat or heavy tails, not volatility clustering. Therefore statement I is not correct.
Statement II is not correct. Where VaR is calculated at low levels of confidence, VaR based on normal mixtures may be lower than that under a normal assumption. This is no different than for other fat tailed distributions.
Statement III is correct. In situations where multiple market scenarios can unfold with a given probability, and each scenario is normal, we can express the result with a normal mixture where the underlying normal distributions have the probabilities of the different scenarios.
NEW QUESTION 57
Which of the following statements are correct in relation to the financial system just prior to the current financial crisis:
I. The system was robust against small random shocks, but not against large scale disturbances to key hubs in the network II. Financial innovation helped reduce the complexity of the financial network III. Knightian uncertainty refers to risk that can be quantified and measured IV. Feedback effects under stress accentuated liquidity problems
- A. II and III
- B. I, II and IV
- C. III and IV
- D. I and IV
Answer: D
Explanation:
Explanation
Statement I is correct. The financial system proved to be stable against small shocks and disturbances, or shocks of a particular type (eg, the dotcom crash, the wars in the Persian Gulf); but rather fragile against other types of shocks, including disturbances to key market participants caused by a worsening of mortgage defaults.Statement II is incorrect. Financial innovation, in particular the slicing and dicing of 'risk' through securitization, significantly increased interrelationships, dependence on the same risk factors, and the complexity of the system as a whole.Statement III is incorrect. A distinction is sometimes made between risk that is knowable, measureable, and quantifiable through parameters; and uncertainty, where the parameters are not known at all. The latter is called 'Knightian uncertainty' after the name of the scholar who came up with the distinction between the two.Statement IV is correct. Feedback effects had the greatest impact on liquidity which was tended to be hoarded, and on asset prices that tumbled as market participants tried to sell assets to become more liquid.Thus, choice is a the correct answer.
NEW QUESTION 58
If the odds of default are 1:5, what is the probability of default?
- A. 12.00%
- B. 50.00%
- C. 16.67%
- D. 20.00%
Answer: C
Explanation:
Explanation
Odds are the ratio between the probability of the occurence of an event to the probability that the event does not occur.
If odds are H, then p = H/(1 + H) and H = p/(1-p). In this case the odds are 1:5, or 1/5, therefore the correct answer is Choice 'a', equal to (1/5)/(1 + 1/5) = 1/6 = 16.67%. All other choices are incorrect.
NEW QUESTION 59
The standard error of a Monte Carlo simulation is:
- A. None of the above
- B. C
- C. Zero
- D. Proportional to the inverse of the square root of the sample size
- E. The same as that for a lognormal distribution
Answer: B
Explanation:
Explanation
When we do a Monte Carlo simulation, the statistic we obtain (eg, the expected price) is an estimate of the real variable. The difference between the real value (which would be what we would get if we had access to the entire population) and that estimated by the Monte Carlo simulation is measured by the 'standard error', which is the standard deviation of the difference between the 'real' value and the simulated value (ie, the 'error').
As we increase the number of draws in a Monte Carlo simulation, the closer our estimate will be to the true value of the variable we are trying to estimate. But increasing the sample size does not reduce the error in a linear way, ie doubling the sample size does not halve the error, but reduces it by the inverse of the square root of the sample size. So if we have a sample size of 1000, going up to a sample size of 100,000 will reduce the standard error by a factor of 10 (and not 100), ie, SQRT(1/100) = 1/10. In other words, standard error is proportional to 1/N, where N is the sample size.
Therefore Choice 'c' is correct and the others are incorrect.
NEW QUESTION 60
For a corporate bond, which of the following statements is true:
I. The credit spread is equal to the default rate times the recovery rate II. The spread widens when the ratings of the corporate experience an upgrade III. Both recovery rates and probabilities of default are related to the business cycle and move in opposite directions to each other IV. Corporate bond spreads are affected by both the risk of default and the liquidity of the particular issue
- A. III and IV
- B. IV only
- C. I, II and IV
- D. III only
Answer: A
Explanation:
Explanation
The credit spread is equal to the default rate times the loss given default, or stated another way, default rate times (1 - recovery rate). It is not equal to the default rate times the recovery rate. Therefore statement I is not correct.
When ratings are upgraded by rating agencies, the spread contracts and not widen. Therefore statement II is not correct.
Both recovery rates and probabilities of default are related to the business cycle, and they move in opposite directions. Economic recessions witness an increase in the default rate and a decrease in the recovery rate, and economic expansions result in a decrease in the default rate and an increase in the recovery rates when default does happen. Therefore statement III is correct.
Bond spreads incorporate both the risk of default, but also considerations of liquidity in the case of corporate bonds. Hence statement IV is correct.
NEW QUESTION 61
Under the standardized approach to determining operational risk capital, operations risk capital is equal to:
- A. a varying percentage, determined by the national regulator, of the gross revenue of each of the bank's business lines
- B. 15% of the average gross income (considering only the positive years) of the past three years
- C. a fixed percentage (different for each business line) of the gross income of the eight specified business lines, averaged over three years
- D. a fixed percentage of the latest gross income of the bank
Answer: C
Explanation:
Explanation
Choice 'd' is the correct answer, as laid down in the Basel II document. The other choices are incorrect.
NEW QUESTION 62
A risk analyst uses the GARCH model to forecast volatility, and the parameters he uses are = 0.001%, = 0.05 and = 0.93. Yesterday's daily volatility was calculated to be 1%. What is the long term annual volatility under the analyst's model?
- A. 0.25 %
- B. 7.94 %
- C. 0.22 %
- D. 3.54 %
Answer: D
Explanation:
Explanation
The correct answer is choice 'a'
Recall the following summary of the GARCH model. The long term variance in a GARCH model is given by
/(1 - - ). In this case, this works out to =SQRT(0.001/(1 - 0.05 - 0.93)) * SQRT(250) = 3.54%. Yesterday's volatility of 1% is irrelevant to the question.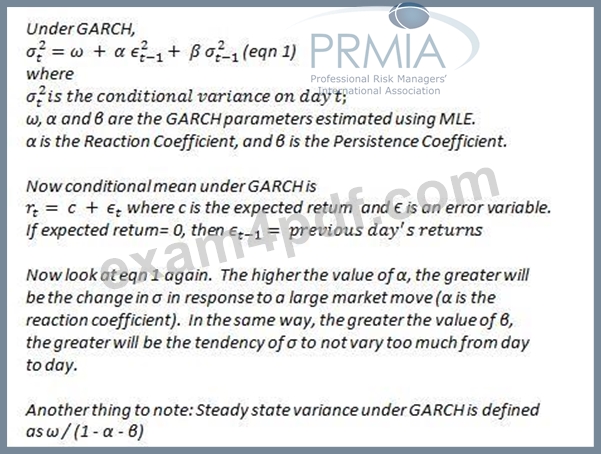
NEW QUESTION 63
Which of the following situations are not suitable for applying parametric VaR:
I. Where the portfolio's valuation is linearly dependent upon risk factors II. Where the portfolio consists of non-linear products such as options and large moves are involved III. Where the returns of risk factors are known to be not normally distributed
- A. All of the above
- B. I and II
- C. I and III
- D. II and III
Answer: D
Explanation:
Explanation
Parametric VaR relies upon reducing a portfolio's positions to risk factors, and estimating the first order changes in portfolio values from each of the risk factors. This is called the delta approximation approach. Risk factors include stock index values, or the PV01 for interest rate products, or volatility for options. This approach can be quite accurate and computationally efficient if the portfolio comprises products whose value behaves linearly to changes in risk factors. This includes long and short positions in equities, commodities and the like.
However, where non-linear products such as options are involved and large moves in the risk factors are anticipated, a delta approximation based valuation may not give accurate results, and the VaR may be misstated. Therefore in such situations parametric VaR is not advised (unless it is extended to include second and third level sensitivities which can bring its own share of problems).
Parametric VaR also assumes that the returns of risk factors are normally distributed - an assumption that is violated in times of market stress. So if it is known that the risk factor returns are not normally distributed, it is not advisable to use parametric VaR.
NEW QUESTION 64
There are two bonds in a portfolio, each with a market value of $50m. The probability of default of the two bonds over a one year horizon are 0.03 and 0.08 respectively. If the default correlation is zero, what is the one year expected loss on this portfolio?
- A. $5.5m
- B. $1.38m
- C. $11m
- D. $5.26m
Answer: A
Explanation:
Explanation
The probabilities of default of the two bonds are independent (as indicated by a zero default correlation). The various possible states of the portfolio are as follows:
First bond defaults, and the second does not: Probability * Loss = 0.03*0.92 * $50m = $1.38m Second bond defaults, and the first does not: Probability * Loss = 0.97*0.08 * $50m = $3.88m Both bonds default: Probability * Loss = 0.03*0.08 * $100m = $0.24m Thus total expected loss on this portfolio = $5.5m. Since recovery rates are not provided, those should be assumed to be zero.
There is an easier way to solve this as well: default correlation does not affect expected losses, but their volatility. You can calculate the expected losses of the two bonds and add them up, ie, $50m*0.03 + $50m
*0.08 = $5.5m
NEW QUESTION 65
Which of the following are considered properties of a 'coherent' risk measure:
I. Monotonicity
II. Homogeneity
III. Translation Invariance
IV. Sub-additivity
- A. All of the above
- B. II and III
- C. I and III
- D. II and IV
Answer: D
Explanation:
Explanation
All of the properties described are the properties of a 'coherent' risk measure.
Monotonicity means that if a portfolio's future value is expected to be greater than that of another portfolio, its risk should be lower than that of the other portfolio. For example, if the expected return of an asset (or portfolio) is greater than that of another, the first asset must have a lower risk than the other. Another example:
between two options if the first has a strike price lower than the second, then the first option will always have a lower risk if all other parameters are the same. VaR satisfies this property.
Homogeneity is easiest explained by an example: if you double the size of a portfolio, the risk doubles. The linear scaling property of a risk measure is called homogeneity. VaR satisfies this property.
Translation invariance means adding riskless assets to a portfolio reduces total risk. So if cash (which has zero standard deviation and zero correlation with other assets) is added to a portfolio, the risk goes down. A risk measure should satisfy this property, and VaR does.
Sub-additivity means that the total risk for a portfolio should be less than the sum of its parts. This is a property that VaR satisfies most of the time, but not always. As an example, VaR may not be sub-additive for portfolios that have assets with discontinuous payoffs close to the VaR cutoff quantile.
NEW QUESTION 66
An operational loss severity distribution is estimated using 4 data points from a scenario. The management institutes additional controls to reduce the severity of the loss if the risk is realized, and as a result the estimated losses from a 1-in-10-year losses are halved. The 1-in-100 loss estimate however remains the same.
What would be the impact on the 99.9th percentile capital required for this risk as a result of the improvement in controls?
- A. The capital required will decrease
- B. The capital required will increase
- C. The capital required will stay the same
- D. Can't say based on the information provided
Answer: B
Explanation:
Explanation
This situation represents one of the paradoxes in estimating severity that one needs to be aware of - the improvement in controls reduces the weight of the body/middle of the distribution and moves it towards the tails (as the total probability under the curve must stay at 100%) and the distribution becomes more heavy tailed. As a result, the 99.9th percentile loss actually increases. instead of decreasing, creating a counterintuitive result. Therefore the correct answer is that the capital required will increase.
If scenario analysis produces such a result, the analyst must question if the 1 in 100 year loss severity is still accurate. If the new control has reduced the severity in the body of the distribution, the question as to why the more extreme losses have not changed should be raised.
NEW QUESTION 67
Which of the following statements are true ?
I. Risk governance structures distribute rights and responsibilities among stakeholders in the corporation II. Cybernetics is the multidisciplinary study of cyber risk and control systems underlying information systems in an organization III. Corporate governance is a subset of the larger subject of risk governance IV. The Cadbury report was issued in the early 90s and was one of the early frameworks for corporate governance
- A. All of the above
- B. II and III
- C. I, II and IV
- D. I and IV
Answer: D
Explanation:
Explanation
Governance structures specify the policies, principles and procedures for making decisions about corporate direction. They distribute rights and responsibiliies among stakeholders that typically include executive management, employees, the board etc. Statement I is therefore correct.
"Cybernetics is a transdisciplinary approach for exploring regulatory systems, their structures, constraints, and possibilities. In the 21st century, the term is often used in a rather loose way to imply "control of any system using technology" (Wikipedia). Governance literature has been affected by cybernetics, which is not the same thing as information security or cyber security. Statement II is incorrect.
Corporate governance includes risk governance, and not the other way round. Therefore statement III is incorrect.
The Cadbury Report, titled Financial Aspects of Corporate Governance, was a report issued in the UK in December 1992 by "The Committee on the Financial Aspects of Corporate Governance". The report is eponymous with the chair of the committee, and set out recommendations on the arrangement of company boards and accounting systems to mitigate corporate governance risks and failures. Statement IV is therefore correct.
NEW QUESTION 68
Which of the following statements are true?
I. Retail Risk Based Pricing involves using borrower specific data to arrive at both credit adjudication and pricing decisions II. An integrated 'Risk Information Management Environment' includes two elements - people and processes III. A Logical Data Model (LDM) lays down the relationships between data elements that an organization stores IV. Reference Data and Metadata refer to the same thing
- A. All of the above
- B. I and III
- C. II and IV
- D. I, II and III
Answer: B
Explanation:
Explanation
Statement I is correct. Retail Risk Based Pricing (RRBP) involves the use of borrower specific data (such as FICO scores, average balances etc) to arrive at credit decisions. These 'retail' credit decisions may include decisions on whether to grant a line of credit, a mortgage, issue a credit card, or any of the various other retail activities a bank may be dealing with. At the same time, this data can also be used to price the product, in addition to providing a yes or no credit decision so that risky borrowers are charged more than less risky borrowers.
Statement II is not correct, because an integrated Risk Information Management Environment includes three elements - people, processes and technology (and not just people and processes).
Statement III is correct. An LDM is a blue print of an organization's data, and describes the relationships between the various data elements.
Statement IV is not correct because reference data and metadata are not the same thing. Reference data refers to relatively static data, such as customer name (while actual transactions may not be so static). Metadata refers to data about data, and is stored in a data dictionary.
Therefore Choice 'b' is the correct answer and the rest are incorrect.
NEW QUESTION 69
Which of the following is a measure of the level of capital that an institution needs to hold in order to maintain a desired credit rating?
- A. Economic capital
- B. Book value
- C. Shareholders' equity
- D. Regulatory capital
Answer: A
Explanation:
Explanation
Economic capital is a measure of the level of capital needed to maintain a desired credit rating. Regulatory capital is the amount of capital required to be held by regulation, and this may be quite different from economic capital. Book value is an accounting measure reflecting the assets minus liabilities as measured per accounting rules, this is often expressed per share. Shareholders' equity is a narrow term which is the amount of capital attributable to the shareholders and includes paid up capital and reserves but not long term debt or other non-equity funding.
Therefore Choice 'b' is the correct answer.
NEW QUESTION 70
If the cumulative default probabilities of default for years 1 and 2 for a portfolio of credit risky assets is 5% and 15% respectively, what is the marginal probability of default in year 2 alone?
- A. 11.76%
- B. 10.00%
- C. 10.53%
- D. 15.79%
Answer: C
Explanation:
Explanation
One way to think about this question is this: we are provided with two pieces of information: if the portfolio is worth $100 to start with, it will be worth $95 at the end of year 1 and $85 at the end of year 2. What it is asking for is the probability of default in year 2, for the debts that have survived year 1. This probability is
$10/$95 = 10.53%. Choice 'b' is the correct answer.
Note that marginal probabilities of default are the probabilities for default for a given period, conditional on survival till the end of the previous period. Cumulative probabilities of default are probabilities of default by a point in time, regardless of when the default occurs. If the marginal probabilities of default for periods 1, 2... n are p1, p2...pn, then cumulative probability of default can be calculated as Cn = 1 - (1 - p1)(1-p2)...(1-pn). For this question, we can calculate the probability of default for year 2 as [1 - (1 - 5%)(1 - 10.53%)] = 15%.
NEW QUESTION 71
There are two bonds in a portfolio, each with a market value of $50m. The probability of default of the two bonds are 0.03 and 0.08 respectively, over a one year horizon. If the probability of the two bonds defaulting simultaneously is 1.4%, what is the default correlation between the two?
- A. 25%
- B. 40%
- C. 0%
- D. 100%
Answer: A
Explanation:
Explanation
Probability of the joint default of both A and B =
We know all the numbers except default correlation, and we can solve for it.
Default Correlation*SQRT(0.03*(1 - 0.03)*0.08*(1 - 0.08)) + 0.03*0.08 = 0.014.
Solving, we get default correlation = 25%
NEW QUESTION 72
Which of the following cannot be used to address the issue of heavy tails when modeling market returns
- A. Student's t-distribution
- B. Normal mixtures
- C. EVT
- D. EWMA
Answer: D
Explanation:
Explanation
Normal mixtures, EVT and the t-distribution are all possible solutions addressing the issue of heavy tails in financial returns.
EWMA and GARCH address volatility clustering, which is the other problem when doing risk calculations.
Therefore Choice 'b' is the correct answer as EWMA is not used to address heavy tails but volatility clustering.
NEW QUESTION 73
Which of the following represent the parameters that define a VaR estimate?
- A. confidence level and the holding period
- B. confidence level, the holding period and expected volatility
- C. trading position and distribution assumption
- D. confidence level and the underlying stochastic process
Answer: A
Explanation:
Explanation
VaR is specified by just two parameters - the holding period, and the confidence level. We speak of, for example, a 10-day VaR at the 95% confidence level. No other parameters are required. Therefore Choice 'd' is the correct answer and the others are incorrect.
NEW QUESTION 74
Which of the following statements are true:
I. Common scenarios for stress tests include the 1997 Asian crisis, the Russian default in 1998 and other well known economic stress situations.
II. Stress tests provide the assurance that an institution's worst case losses will be covered.
III. Performing stress tests is highly recommended but is not mandated under Basel II.
IV. Historical events can be modeled quite accurately as they have defined start and end dates.
- A. All of the above
- B. I only
- C. I and II
- D. I, III and IV
Answer: B
Explanation:
Explanation
Stress tests can cover known events, but since the future is unknown, and new events may be entirely different from what has happened in the past, they provide no assurance that an institution's worst case losses would be covered. Hence II is false.
Stress testing is required to be performed as part of Basel II, and therefore III is false.
Historical events do not have sharply defined start and end dates. Often, even after a crises ends, its after effects may continue to affect the markets for a long time. In such cases, it may be difficult to define the start and end of the crises. In many cases, the crises may persist for months or even years, making it difficult for the risk manager to identify a time period that covers the essence of the crises, and yet is focused enough to constitute a plausible scenario. Therefore IV is false too. Only I is true, and the correct answer is Choice 'b'.
NEW QUESTION 75
......
Use Valid New 8008 Test Notes & 8008 Valid Exam Guide: https://www.exam4pdf.com/8008-dumps-torrent.html
